Author: Davis Finke, CFA
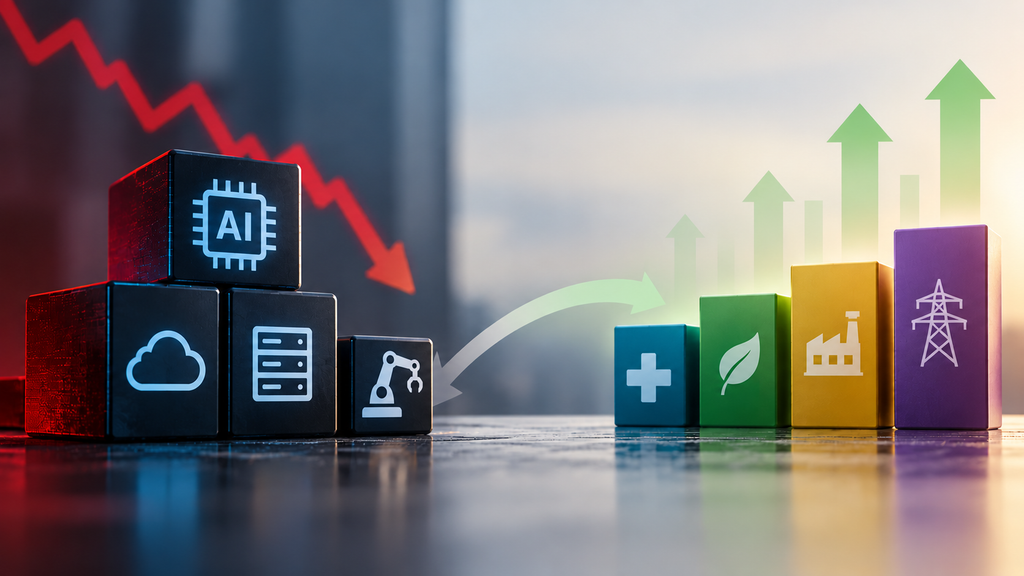
Third-quarter earnings reports from several mega-cap technology and AI-related companies were the primary focus for investors this week, as mixed results from Microsoft, Alphabet, and Amazon raised further questions about the growing cost of AI investments. Microsoft reported better-than-expected results for the quarter ended September 30, with both revenue and earnings beating forecasts. Alphabet and Amazon, however, missed on both revenue and earnings, with Alphabet reporting negative free cash flow of approximately $9 billion. This marked the first time Alphabet has reported two consecutive quarters of negative free cash flow, as the company has rapidly accelerated spending on AI infrastructure. Elevated spending on AI infrastructure was a consistent theme across all three companies this week and has become an increasingly significant area of concern for investors. While the concern doesn’t necessarily relate to the demand for AI, the extraordinary levels of spending have raised questions about whether these investments will generate sufficient returns to justify the costs, particularly in the near term. These concerns, combined with the mixed earnings reports, contributed to a rotation out of technology and into other areas of the market, where strong corporate earnings have provided support.
Although each of the three major U.S. equity indexes finished the week lower, the negative performance masked broad-based strength across much of the market. Corporate earnings have been an important source of that strength, with 60% of the companies in the S&P 500 having reported third-quarter results as of today. Of those companies, 82% have reported earnings above estimates. The strong performance has been broad-based, with all 11 sectors reporting year-over-year earnings growth and seven reporting double-digit growth, providing investors with opportunities outside of technology amid growing concerns surrounding AI spending. This rotation was evident in the market’s performance for the week, with nine of the 11 sectors finishing higher. Leading the way was health care, which gained over 3%, followed by materials, up 2.82%, and utilities, up 2.09%. Five additional sectors gained more than 1% for the week. The only sectors to finish lower were communication services, down 5.29%, and information technology, down 2.01%. However, the significant influence of large technology and communication services companies on the major indexes meant that weakness in these areas outweighed gains elsewhere in the market. The tech-heavy Nasdaq was the worst performer, down 1.98% for the week, followed by the Dow Jones, down 0.83%, and the S&P 500, down 0.56%. The contrast between the negative performance of the major indexes and the broad-based strength across much of the market highlights the importance of a well-diversified portfolio during periods of changing market sentiment.
Looking ahead to next week, earnings will continue to be a primary focus for investors. An additional 140 S&P 500 companies are scheduled to report, headlined by Apple and semiconductor company Advanced Micro Devices. Also on the calendar is the October jobs report, which will provide investors with updated data on unemployment and payroll growth. Lastly, the midterm elections are on Tuesday, potentially adding another element of volatility to markets. Historically, however, market performance following midterm elections has been quite strong. Since 1934, the 12 months following every midterm election have been positive for U.S. equities, with an average return of 21%.