Author: Davis Finke, CFA
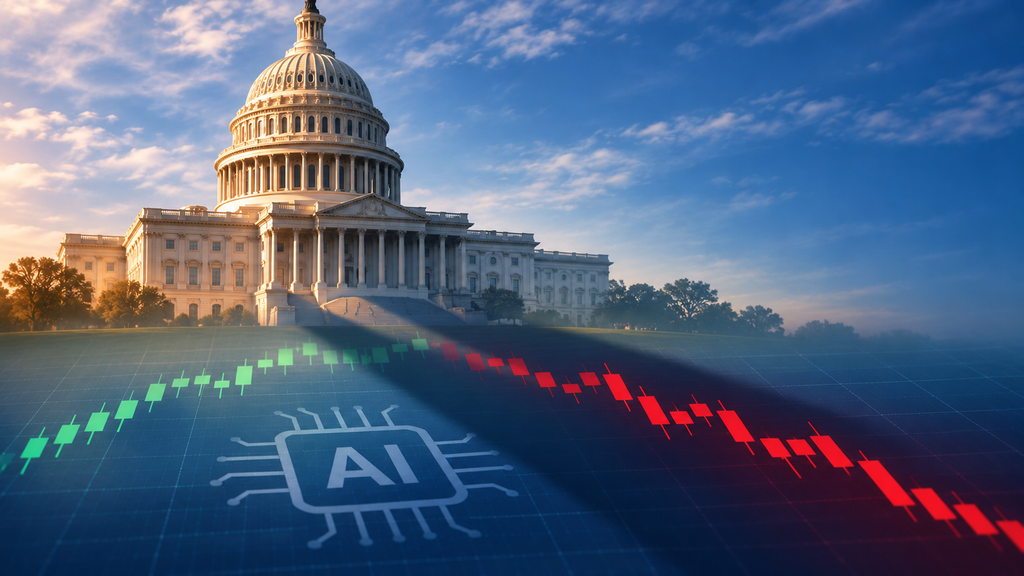
Equity markets closed out a volatile week following Tuesday’s midterm elections, which resulted in Democrats winning majorities in both the Senate and the House of Representatives. The market’s immediate reaction on Wednesday was positive, with each of the three major equity indexes advancing. Wednesday’s gains likely reflected investors’ relief in the certainty of the election outcome following weeks of political unease that had been hanging over Wall Street. The bond market also benefited on Wednesday, as investors weighed the potential for reduced debt-financed stimulus, along with a sharp decline in oil prices, to help limit upward pressure on inflation and interest rates. However, the election results also raised concerns about increased scrutiny of the technology sector, particularly regarding the rapid expansion of data centers needed to support AI infrastructure. These concerns intensified on Thursday, contributing to a sharp selloff that wiped out Wednesday’s gains and pushed overall market performance for the week into negative territory.
The selloff came as investors were already questioning the sustainability and potential returns of the large-scale investments being made in AI infrastructure. The prospect of additional regulatory scrutiny and potential delays to data-center development compounded these concerns, placing further pressure on technology and AI-related stocks. The Nasdaq-100 index, which has significant exposure to these companies, fell by approximately 6.4% on Thursday, marking its worst single-day percentage decline of 2026. The technology sector was particularly hard hit, with its widely followed sector ETF declining approximately 8%, its worst trading day since March 2020. The weakness extended beyond technology, with all 11 S&P 500 sectors declining on Thursday and dragging the broader indexes lower. As a result, the Nasdaq was the worst performer for the week, finishing down 5.12%, followed by the S&P 500 down 2.69% and the Dow Jones down 0.94%. At the sector level, energy was the worst performer, down 11.95% for the week, followed by technology down 8.20% and industrials down 2.79%. On the other hand, several sectors finished the week higher, led by communications services gaining 4.90% and both consumer discretionary and real estate each gaining 1.90%. Financials, consumer staples, and health care also recorded gains for the week.
While the Nasdaq is now down more than 10% from its record high reached just a month ago, the index is still up over 6% year to date. As investors continue to assess the potential for increased regulatory scrutiny and a slowdown in AI infrastructure development, volatility within the technology sector could persist over the coming months. However, the broader economic and corporate backdrop remains supportive of U.S. equities as a whole. Friday’s employment report for October showed a much better-than-expected gain of 165,000 jobs, with strong hiring across multiple areas of the economy. Job gains for the previous two months were also revised higher, while the unemployment rate fell to 4.1% and initial jobless claims matched their lowest level since 1969. Corporate profits also remain strong, with 84% of S&P 500 companies that have reported third-quarter results beating earnings forecasts, above both the 5-year and 10-year averages. History also provides some encouraging perspective, as the 12 months following midterm elections have produced positive market returns in every instance dating back to 1934, with average gains exceeding 20%. While historical performance is no guarantee of future results, it reinforces the importance of maintaining a longer-term perspective during periods of market volatility. With the technology sector potentially facing continued headwinds, it remains important for investors to maintain diversified portfolios to help limit concentration risk while remaining positioned to benefit from opportunities across different sectors.